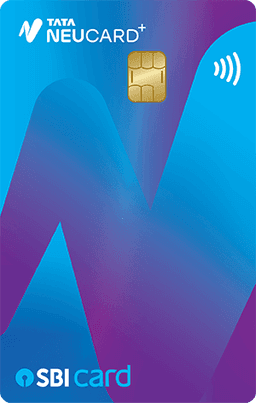
Tata Neu Plus SBI Card Review 2026: 2% on Tata Brands, 1% Including UPI, ₹499 Fee & FAQs
Tata Neu Plus SBI Card costs ₹499 and pays 2% at Tata Neu and partner brands and 1% on everything else — including UPI, in NeuCoins worth ₹1 each. But UPI earning stops at 500 NeuCoins a month. Welcome coins cover the fee. Full maths, fees and FAQs.
The Tata Neu Plus SBI Card is the entry rung of SBI's Tata Neu range: ₹499 a year, 2% at Tata Neu and partner Tata brands and 1% on everything else, in NeuCoins worth ₹1 each.
Its quiet strength is not the 2%. It is that the 1% base rate includes UPI transactions — which most Indian co-brands exclude — in a currency worth a full rupee. The 499 welcome NeuCoins match the ₹499 fee exactly, so year one is free.
Tata Neu Plus SBI Card Quick Overview
| **Card type** | Entry retail ecosystem co-brand — Tata Neu |
|---|---|
| **Best for** | Tata shoppers, and anyone who pays by UPI and wants it rewarded |
| **Joining / annual fee** | ₹499 + GST, same on renewal — **no spend-based waiver** |
| **Network** | Visa, Mastercard or RuPay |
| **Tata Neu and partner Tata brands** | **2%** — uncapped, non-EMI only |
| **Everything else** | **1%** — uncapped except for five capped categories, below |
| **Reward value** | **₹1 per NeuCoin** — published by both SBI and Tata |
| **Welcome benefit** | 499 NeuCoins — covers the fee |
| **Lounge access** | 4 domestic a year — **gated on spend** |
| **Milestones** | None |
Eligibility Criteria
SBI Card publishes no age or income threshold. Approval rests on its own assessment of income, credit history and internal scoring. Indian residency and a valid PAN are required. Add-on cards are free.
The 1% Includes UPI — And That Is the Real Story
SBI states it explicitly: the base rate applies to UPI transactions as well as card transactions.
Most Indian co-brands do the opposite. The Reliance SBI cards exclude UPI from their accelerated rates, dropping a QR-code payment from 1.25% to 0.25%. Many others simply do not pay on UPI at all. Here UPI spend earns the same rate as card spend — but only up to 500 NeuCoins a month, which is ₹50,000 of UPI spend. Past that, UPI earns nothing for the rest of the month.
For anyone who routinely pays by QR code, that changes what the card is worth. It works at the small merchants, kirana stores and roadside outlets where a card terminal is rare and a QR code is universal — places most reward cards simply do not reach.
And 1% in points worth a full rupee is genuinely competitive at ₹499. SBI's own SimplySAVE, at the same fee, pays 0.17% outside four narrow categories — about a sixth as much.
Reward Structure
| Spend | Rate | Cap |
|---|---|---|
| **Tata Neu and partner Tata brands** (non-EMI) | **2%** | **None** |
| **Everything else** | **1%** | **None**, except the five categories below |
| Fuel, cash advances | **0%** | — |
NeuCoins are worth ₹1 each — published, not inferred. Both SBI and Tata state "1 NeuCoin = Re. 1 savings" outright, so the percentages above are true percentages.
Three conditions worth catching
EMI is excluded from the 2% rate. SBI's wording is "on Non-EMI spends at the Tata Neu App/Website and partner Tata brands". Converting a Tata Neu purchase to EMI forfeits the accelerated rate.
There is an "extra 5% on select categories" that cannot be pinned down. SBI says an additional 5% applies to select category spends on the Tata Neu app or website — 7% in total — without publishing which categories qualify. Treat it as upside to check at the point of purchase, not a rate to plan around.
The partner brand list is wider than most tools recognise. Tata Neu, Croma, BigBasket, Tata CLiQ, Westside and Air India are widely recognised. Tata's actual list also includes Tata 1mg, Qmin, IHCL hotels and Tata Play, so comparison engines will understate the card at those brands.
Lounge Access Is Gated on Previous-Quarter Spend
The headline is 4 domestic airport lounge accesses a year, 1 per quarter. There is no international lounge access.
But access in any quarter requires ₹50,000 of spend in the previous quarter.
- A new cardholder gets nothing in their first quarter — there is no previous quarter to qualify on.
- Any quarter you fall short costs the following quarter's visit, and it does not roll forward.
- Sustaining all four visits means ₹2 lakh a year, spread evenly across quarters.
It is a quarterly test, not an annual one.
No Fee Waiver, No Milestones
No spend-based fee reversal is published for either Tata Neu card at any level — unusual in SBI's range.
What replaces it: 499 welcome NeuCoins, credited within 15 days of joining-fee realisation, matching the ₹499 fee exactly. Year one is free for anyone who pays the fee.
From year two the ₹499 is a real cost. At 1% that needs ₹50,000 of annual spend to recover — a very low bar.
There is no milestone programme on either Tata Neu card.
Worked Example
Illustrative, at ₹22,000 a month — ₹2.64 lakh a year, holding the lounge gate:
| Category | Monthly spend | Rate | Value |
|---|---|---|---|
| Tata Neu, Croma, BigBasket, Westside | ₹5,000 | 2% | ₹100 |
| Everything else, including UPI | ₹15,500 | 1% | ₹155 |
| Fuel | ₹1,500 | 0% | ₹0 |
| **Monthly total** | **₹22,000** | **₹255 — 1.16%** |
Annual tally:
| NeuCoins earned | ₹3,060 |
|---|---|
| Welcome NeuCoins (year one) | ₹499 |
| **Year-one total** | **₹3,559** |
| **Steady state** | **₹3,060** |
| Annual fee | ₹499 (never waived) |
| **Net, steady state** | **₹2,561 — 0.97% of spend** |
Plus 4 domestic lounge visits (₹66,000 a quarter clears the ₹50,000 gate).
Note the base rate does most of the work: ₹1,860 of the ₹3,060 comes from ordinary spending at 1%. The Tata band is a bonus, not the point.
Where You Won't Earn
| Excluded | Note |
|---|---|
| **Fuel** | MCC 5172, 5541, 5542, 5983 |
| **Cash advances** | 2.5% fee, minimum ₹500, interest from day one |
| **EMI at Tata Neu** | Forfeits the 2% rate specifically |
The fuel surcharge waiver is the whole fuel benefit: 1% reversed on transactions between ₹500 and ₹4,000, capped at ₹250 per statement cycle — more generous than the ₹100 most SBI cards allow, and notable on a ₹499 card.
SBI's range-wide transaction fees apply: ₹199 per rent payment, 1% on wallet loads above ₹1,000, 1% on utility payments once the cycle total passes ₹50,000, and 1% on education payments through third-party apps.
Fees and Charges
| Charge | Amount |
|---|---|
| Joining fee | ₹499 + GST |
| Renewal fee | ₹499 + GST — **no spend-based reversal at any level** |
| Add-on card fee | Nil |
| Finance charge | 3.75% per month — **45% per annum** |
| Interest-free period | 20 to 50 days; none if any part of last month's bill is unpaid |
| Forex markup | 3.5% |
| Cash advance fee | 2.5%, minimum ₹500 |
| Fuel surcharge waiver | 1% on ₹500–₹4,000, max ₹250 per cycle |
| Late payment | ₹100 to ₹1,300 by balance |
| Overlimit | 2.5%, minimum ₹600 |
| GST | 18% on all of the above |
NeuCoin expiry is governed by Tata Neu's own rules, not SBI's 24-month clock. SBI publishes no expiry, so check Tata Neu's terms rather than assuming they last indefinitely.
Plus vs Tata Neu Infinity
| **Tata Neu Plus SBI Card** | Tata Neu Infinity SBI Card | |
|---|---|---|
| Annual fee | ₹499 | ₹1,499 |
| Tata Neu and partner brands | 2% | **5%** |
| Everything else (incl. UPI) | 1% | **1.5%** |
| Welcome NeuCoins | 499 (covers fee) | 1,499 (covers fee) |
| Domestic lounge | 4 a year | **8 a year** |
| International lounge | **None** | Included |
| Lounge gate | ₹50,000 previous quarter | ₹75,000 previous quarter |
| Fee waiver | None | None |
Break-even on the ₹1,000 fee difference:
- On the Tata band alone: ₹1,000 ÷ 3 points = ₹33,333 of annual Tata spend
- On the base rate alone: ₹1,000 ÷ 0.5 points = ₹2,00,000 of annual general spend
₹33,000 a year across BigBasket, Croma and Westside is not much, so for most people the Infinity is the better card. The Plus makes sense for a light spender who rarely buys from Tata brands but still wants UPI rewarded at 1%.
Is the Tata Neu Plus SBI Card Worth It?
Yes, as a cheap UPI-earning card — within limits. 1% on everything including QR-code payments, in points worth a full rupee, at ₹499 covered by the welcome coins. Just note UPI earning stops at 500 NeuCoins (₹50,000 of UPI spend) a month.
Yes, if you shop at Tata brands occasionally. 2% at BigBasket, Croma and Westside is solid for an entry card.
Consider the Infinity instead if your annual Tata spend exceeds about ₹33,000 — the break-even is low enough that most Tata shoppers should step up.
No, if your annual spend is under ₹50,000. With no fee waiver at any level, the ₹499 is a real cost from year two, though a low one.
Watch the lounge gate. ₹50,000 a quarter, every quarter, or you lose the following quarter's visit. A new cardholder gets nothing in their first quarter.
Frequently Asked Questions
What is the annual fee of the Tata Neu Plus SBI Card? ₹499 plus GST, on joining and renewal. No spend-based fee reversal is published at any level. The 499 welcome NeuCoins match the fee exactly, so year one is free.
What is the reward rate? 2% value back as NeuCoins on non-EMI spends at Tata Neu and partner Tata brands, and 1% on everything else — including UPI transactions. Neither rate is capped.
Do UPI payments earn rewards? Yes, at the full 1% base rate — SBI states the UPI inclusion explicitly. Most Indian co-brands exclude UPI or pay less on it.
What is a NeuCoin worth? ₹1 — both SBI and Tata state "1 NeuCoin = Re. 1 savings". That makes NeuCoins worth four times an ordinary SBI Reward Point.
Does EMI earn the 2% rate? No. SBI's wording is "on Non-EMI spends", so converting a Tata Neu purchase to EMI forfeits the accelerated rate.
Which brands count as partner Tata brands? Tata Neu, Croma, BigBasket, Tata CLiQ, Westside and Air India are the widely recognised ones. Tata's list also includes Tata 1mg, Qmin, IHCL hotels and Tata Play.
How does the lounge access work? 4 domestic visits a year, 1 per quarter — but access in any quarter requires ₹50,000 of spend in the previous quarter. A new cardholder gets nothing in their first quarter. There is no international lounge access.
Should I take the Plus or the Infinity? Break-even on the Tata band is only about ₹33,000 of annual Tata spend, so most Tata shoppers should take the Infinity. The Plus suits a light spender who rarely buys from Tata brands but still wants UPI rewarded.
Cards Mentioned in This Article