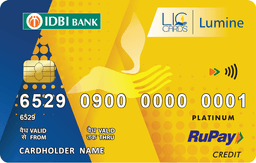
LIC IDBI Lumine Platinum Review 2026: Lifetime Free at 0.75% — but Royale Signature Beats It
The LIC IDBI Lumine Platinum is lifetime free and earns 0.75%. IDBI's own page misnames it as the Eclat card. Royale Signature matches its rate and beats it everywhere else. Full review.
The LIC IDBI Lumine Platinum is lifetime free and earns 3 Delight Points per ₹100 — 0.75%.
That matches IDBI's Royale Signature exactly. Everything else about the two cards does not.
LIC IDBI Lumine Platinum Credit Card Quick Overview
| **Card type** | Entry LIC co-brand |
|---|---|
| **Best for** | An LIC customer who wants a free card |
| **Joining / renewal fee** | Nil, same on renewal |
| **Network** | RuPay |
| **Base reward rate** | **0.75%** |
| **Reward currency** | Delight Points, valued at ₹0.25 each |
| **Lounge access** | None published |
| **Forex markup** | 3.5% |
Reward Structure: How You Earn
IDBI's reward currency is the Delight Point, and one is worth ₹0.25. The bank publishes that figure once, in the Imperium card's FAQ, in square brackets beside the earn rate: '2 Delight Point on every purchase transaction of Rs. 150/- [1 Point = Rs 0.25]'.
Redemption is free. IDBI's MITC states the reward redemption fee is nil for all card variants — so the headline rate is the rate you actually get. That is not true of most of this dataset: AU charges ₹99 + GST per redemption, IDFC ₹99, and BOBCARD sets a ₹1,000 minimum.
3 Delight Points per ₹100 spent — 0.75% at the published ₹0.25 a point.
| Spend | Effective rate |
|---|---|
| Everything else | 0.75% |
| Fuel, rent, wallet loads, government, gaming | **0%** |
IDBI's own page calls this the Eclat card
The Lumine product page reads: 'You will earn 3 Delight Points for every Rs. 100 spent by you using your Eclat Credit Card.'
The rate differs from Eclat's — Eclat earns 4 points per ₹100, Lumine 3 — so this is a copy-paste slip in the sentence rather than a cloned product, and the 3-point rate is taken as correct for Lumine. It is flagged here because it shows the two LIC pages were written from one template, which is worth knowing if you are comparing them closely.
Royale Signature matches the rate and beats everything else
| LIC Lumine | Royale Signature | |
|---|---|---|
| Annual fee | Nil | Nil |
| Earn rate | 0.75% | 0.75% |
| Interest | 3.40%/month | **2.50%/month** |
| Fuel cap | ₹300/month | **₹500/month** |
| Lounge | None | **1/quarter** |
Same rate, same price of zero — and Royale Signature is cheaper to borrow on, waives more fuel surcharge and includes lounge access.
Nine categories earn nothing at all
IDBI publishes the merchant category codes, and the list is harsher than most:
| MCC | Category |
|---|---|
| 4112 | **Passenger railways** |
| 6381, 5960 | Insurance premiums and direct-marketing insurance |
| 9311 | Tax payments |
| 9222 | Fines |
| 6211 | Securities brokers and dealers |
| 5542, 5172, 5983 | Fuel — dispensers, petroleum products, fuel dealers |
Railways earning nothing is worth singling out. IRCTC and passenger rail are a large slice of Indian card spending, and IDBI excludes them outright rather than paying a floor rate. Insurance and tax go the same way — excluded entirely, not capped.
Refunds claw back points. Where a transaction is later reversed or refunded, IDBI debits the corresponding points from your balance.
The interest rate depends on which card you hold
IDBI sets the revolving rate per variant, and the spread is wide enough to matter:
| Card | Monthly | Annual |
|---|---|---|
| Royale Signature | **2.50%** | 30.00% |
| Aspire, Euphoria World, Imperium | 2.90% | 34.80% |
| Winnings, LIC Eclat, LIC Lumine | **3.40%** | 40.80% |
A cardholder who revolves a balance pays a third more on Winnings than on Royale Signature for exactly the same debt.
Fees and charges
Joining fee is nil on all seven cards. So are add-on card fees, and points earned on an add-on are clubbed with the primary card's balance.
Late payment is graduated: nil at ₹500 or below, ₹400 up to ₹5,000, ₹500 up to ₹10,000, ₹750 up to ₹20,000, and ₹950 above that.
Cash advance costs 2.5% or ₹500, whichever is higher, with interest from the transaction date. Over-limit is 2.5%. Foreign currency markup is 3.5% across the range.
The interest-free period is 18 to 48 days, and only if the previous balance was cleared in full.
Balance transfers are not offered — IDBI states plainly that the facility is not currently provided.
One thing to know before closing an IDBI card: Delight Points cannot be redeemed after card closure, irrespective of the balance held. Redeem before you close, not after.
Category Restrictions: Where You Won't Earn
- Where you earn nothing: Earns nothing at all. NINE MERCHANT CATEGORIES EARN NO DELIGHT POINTS, and IDBI publishes the MCCs: 6211 securities brokers and dealers, 6381 insurance premiums, 5960 direct-marketing insurance, 9222 fines, 9311 tax payments, 4112 PASSENGER RAILWAYS, and the three fuel codes 5542 automated fuel dispensers, 5172 petroleum products and 5983 fuel dealers.
RAILWAY BOOKINGS EARNING NOTHING IS WORTH SINGLING OUT — IRCTC and passenger rail are a large category of Indian card spend, and IDBI excludes them outright rather than paying a floor rate. Insurance and tax payments are likewise excluded entirely rather than capped. REVERSALS CLAW BACK POINTS: where a transaction is later reversed or refunded, IDBI debits the corresponding points from the balance.
- Point expiry: IDBI does not state a Delight Points validity period in the readable portion of its MITC. What it does state is that points cannot be redeemed after card closure, irrespective of the balance — so the practical expiry risk is closing the account, not the passage of time.
Fees and Charges
| Charge | Amount |
|---|---|
| Joining fee | Nil |
| Renewal fee | Nil |
| Finance charges | Set per card variant: Royale Signature 2.50% a month (30.00% a year); Aspire, Euphoria World and Imperium Platinum 2.90% (34.80%); Winnings, LIC Eclat and LIC Lumine 3.40% (40.80%). |
| Interest-free period | 18 to 48 days, subject to the transaction date within the billing cycle and to the previous balance having been cleared in full. Not available on cash advances, where a finance charge applies from the transaction date. |
| Minimum amount due | 5% of the statement balance including cash advance, plus 100% of fees and charges, plus 100% of interest and finance charges. IDBI works the arithmetic in the MITC. |
| Cash advance fee | 2.5% of the transaction amount or ₹500, whichever is higher. |
| Cash advance interest | Charged at the card's revolving rate from the transaction date, with no interest-free period. |
| Forex markup | 3.5% cross-currency markup on all international transactions. |
| Late payment | Graduated by statement balance: nil at ₹500 or below; ₹400 above ₹500 up to ₹5,000; ₹500 above ₹5,000 up to ₹10,000; ₹750 above ₹10,000 up to ₹20,000; and ₹950 above ₹20,000. |
| Overlimit | 2.5% of the over-limit amount. |
| Fuel transactions | No fuel transaction fee is published. Note separately that fuel earns NO Delight Points — MCCs 5542, 5172 and 5983 are on IDBI's exclusion list — while a fuel surcharge waiver does apply, capped per variant. |
| Add-on card | Nil on every variant. IDBI's MITC records no joining or annual fee for add-on cards across the range, and Delight Points earned on an add-on card are clubbed with the primary card's balance. |
| Reward redemption | Nil, for all card variants — IDBI charges nothing to redeem Delight Points. |
| EMI processing | EMI conversion is offered on tenures of 3, 6, 9, 12, 18, 24, 30 and 36 months. The processing fee is set out in IDBI's separate EMI Facility Terms and Conditions. |
| GST | 18% on all fees, interest and charges. |
Is the LIC IDBI Lumine Platinum Credit Card Worth It?
If you hold LIC policies and want a free card, Lumine works — but check whether you qualify for Royale Signature first.
If you revolve a balance, the difference is substantial. 3.40% a month against 2.50% is a third more interest for the same debt.
Note that insurance premiums earn nothing on any IDBI card, including this LIC co-brand.
The Eclat, also an LIC co-brand and also free, earns 1.0% — a third more than Lumine — at the same interest rate.
Frequently Asked Questions (FAQs)
Why does the IDBI Lumine page mention the Eclat card? It appears to be a copy-paste slip: the Lumine page describes earning '3 Delight Points for every Rs. 100 spent by you using your Eclat Credit Card'. The rate quoted (3 points) differs from Eclat's actual 4 points per ₹100, so the rate is Lumine's and the card name is the error.
Is LIC Lumine or LIC Eclat the better card? Eclat, on earning — 4 Delight Points per ₹100 (1.0%) against Lumine's 3 (0.75%). Both are lifetime free and both carry IDBI's highest interest rate of 3.40% a month. Eclat also has a ₹500 monthly fuel waiver cap against Lumine's ₹300.
What is an IDBI Delight Point worth? ₹0.25. IDBI publishes the figure in its Imperium Credit Card FAQ. Redemption is free — the MITC states the reward redemption fee is nil for all card variants.
What does not earn Delight Points on IDBI cards? Nine merchant categories: passenger railways (MCC 4112), insurance premiums (6381 and 5960), tax payments (9311), fines (9222), securities brokers (6211) and the three fuel codes (5542, 5172, 5983). Refunded transactions also have their points debited back.
Do IDBI Delight Points expire? IDBI states no validity period in the readable portion of its MITC. It does state that points cannot be redeemed after card closure regardless of the balance — so the real risk is closing the account with points unredeemed.
Cards Mentioned in This Article