HSBC TravelOne Credit Card Review 2026: Transferable Air Miles, 20 Loyalty Partners, Travel with Poi
HSBC TravelOne Credit Card review 2026 — 4 Reward points per ₹100 on flights and forex, 1:1 transfers to 15 airlines and 5 hotel chains, 10 lounge visits a year, ₹4,999 fee waived at ₹8 lakh spend.
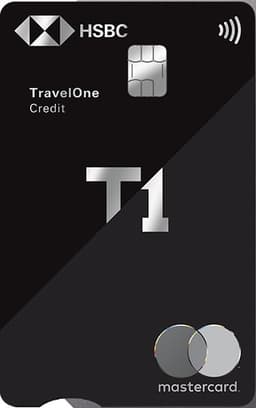
The HSBC TravelOne is a ₹4,999 travel card built around one idea: earn points that move, instantly, into airline miles and hotel loyalty currencies. With the Axis Atlas no longer open to new applicants, it has become the most talked-about mid-premium miles card in India. It suits people who book two or three international trips a year and want flexibility across programmes rather than loyalty to a single airline. It suits almost nobody whose spending is concentrated in fuel, rent, utilities, insurance or tax payments, because none of those earn anything at all.
HSBC TravelOne Credit Card Quick Overview
| Feature | Details |
|---|---|
| Card type | Travel and rewards credit card |
| Best for | Transferable air miles, travel aggregator and hotel bookings, international travel |
| Joining fee | ₹4,999 + GST |
| Annual fee | ₹4,999 + GST, fully reversed on eligible annual spend above ₹8,00,000 |
| Network | Mastercard (World platform) |
| Top reward | 24 Reward points per ₹100 on hotels booked via HSBC Travel with Points |
| Base reward | 2 Reward points per ₹100 on all other eligible spends, uncapped |
| Reward type | Reward points, valued at ₹1 per point on the best redemptions |
| Welcome benefit | ₹1,000 cashback + ₹3,000 Postcard Hotels voucher + 3-month EazyDiner Prime |
| Lounge access | 6 domestic and 4 international visits per year, no spend condition |
Eligibility Criteria
- Aged 18 to 65 for salaried applicants, or 25 to 65 for self-employed applicants
- Minimum annual income of ₹6,00,000 for salaried applicants, or ₹12,00,000 for self-employed applicants
- Indian resident
- Residence or office in Chennai, Gurgaon, Delhi NCR, Pune, Noida, Hyderabad, Mumbai, Bengaluru, Kochi, Coimbatore, Jaipur, Chandigarh, Ahmedabad, Kolkata, Amritsar, Baroda, Indore, Lucknow, Nagpur or Surat
- Documents: latest salary slip if salaried, plus proof of residence, identity proof and PAN card
Welcome Benefit
Download and log on to the HSBC India Mobile Banking app, then spend ₹25,000 within the first 30 days of the account opening, and you receive all three of the following:
- ₹1,000 cashback, credited within 60 days of completing 30 days from card issuance
- A ₹3,000 voucher from The Postcard Hotel, usable at any Postcard property with no blackout dates, bookable only through postcardresorts.com or the reservation line
- A 3-month EazyDiner Prime membership, which HSBC values at ₹1,095
Total stated welcome value is ₹5,095 against a ₹4,999 joining fee, so the first year roughly washes out — but only if the Postcard voucher is actually usable for you. Postcard operates a small luxury portfolio, and if you never stay at one, ₹3,000 of that ₹5,095 evaporates.
The current introductory offer T&C covers applications made between 1 July 2026 and 31 December 2026. Cardholders who have not repaid their minimum payment due within 30 days of the due date are not eligible, and KYC must be current. Only sales transactions count towards the ₹25,000 — finance charges, cash advances and their fees, late payment charges, balance transfers and annual fees do not, and cancelled or refunded transactions are netted off.
Reward Structure: How You Earn
The card runs on HSBC Reward Points. Two headline rates, one milestone, and a separate booking portal that pays far more than either.
| Spend type | Earn rate | Value at ₹1/point | Monthly cap |
|---|---|---|---|
| Flights, airlines, travel aggregators, foreign currency | 4 points per ₹100 | 4% | 50,000 accelerated points |
| All other eligible spends | 2 points per ₹100 | 2% | None |
| Hotels via HSBC Travel with Points | 24 points per ₹100 | 24% | 18,000 accelerated points (shared) |
| Flights and car rentals via HSBC Travel with Points | 16 points per ₹100 | 16% | 18,000 accelerated points (shared) |
Where the ₹1 per point comes from. HSBC's own TravelOne value calculator states that 1 Reward point equals ₹1 when redeemed on Apple products or through Travel with Points, and its worked examples are internally consistent with that: ₹12,00,000 of base spend generates 24,000 points, which the calculator values at ₹24,000. Most airline partners transfer at 1:1, so a point is roughly a mile. Redeem for vouchers or merchandise in the Rewards Marketplace instead and the realised value drops sharply — secondary estimates put voucher redemptions closer to ₹0.20 per point. Everything below assumes you redeem for miles or hotel points.
The accelerated cap. The 4 points per ₹100 rate is capped at 50,000 accelerated points per calendar month, roughly ₹12,50,000 of eligible travel or forex spend. Past that, the next rupee earns the base 2 points per ₹100. This cap is not stated in HSBC's public product copy, which carries only a footnote marker; the 50,000 figure comes from independent card publications and is consistent across several of them.
Travel with Points is the real story. Inside the HSBC India app, the Travel with Points portal — run with Hopper — lets you book flights, hotels and car rentals at sharply accelerated rates. Hotels earn 6X, which works out to 24 points per ₹100. Flights and car rentals earn 16 points per ₹100. Accelerated portal points are capped at 18,000 per calendar month shared across all three categories, which is about ₹75,000 of hotel spend or ₹1,12,500 of flight spend, and they credit within 10 days of settlement. The catch is real: cardholders consistently report that portal fares run above open-market fares, so treat the headline 24% as a ceiling rather than a promise, and price-check before booking. The portal does include a best price guarantee, and users report HSBC honouring it.
Worked example
The uploaded T&C documents carry no rewards worked example, so the following is illustrative, built on HSBC's own value calculator assumptions and the published rates.
Assume a cardholder spending ₹12,00,000 a year, of which ₹1,00,000 is flights, ₹50,000 is hotels, ₹20,000 is car rentals and ₹4,00,000 is foreign currency or other travel spend.
| Component | Spend | Points | Value at ₹1/point |
|---|---|---|---|
| Base earning on all eligible spend | ₹12,00,000 | 24,000 | ₹24,000 |
| Travel with Points uplift (flights, hotels, car rentals) | ₹1,70,000 | 22,800 | ₹22,800 |
| Accelerated uplift on forex and travel category | ₹4,00,000 | 8,000 | ₹8,000 |
| Annual milestone at ₹12,00,000 | — | 10,000 | ₹10,000 |
| **Total** | **64,800** | **₹64,800** |
Against a ₹4,999 fee that is a strong return — but note the ₹8,00,000 waiver threshold means a spender at this level pays no fee at all, and note also that the same profile spending ₹4,00,000 abroad pays roughly ₹16,500 in forex markup plus GST to earn ₹8,000 of accelerated value.
Milestone Benefits
Spend ₹12,00,000 of net eligible spend in an anniversary year and earn 10,000 bonus Reward points, worth ₹10,000 at the best redemption. The anniversary year runs from the card account open date, not the financial year.
Categories that do not count towards the milestone: finance charges, cash advances and cash advance charges, late payment charges, balance transfers, and annual fees. Cancelled or refunded transactions are adjusted for, and only net spends count. Add-on cardholders have no separate milestone eligibility, and cardholders who have not repaid their minimum payment due within 30 days of the due date are ineligible.
Note the asymmetry worth planning around: fuel, rent, utilities and insurance earn zero Reward points but still count towards both the ₹8,00,000 fee waiver and the ₹12,00,000 milestone.
Redemption: 20 Transfer Partners
This is the card's core proposition. Transfers happen inside the HSBC India app and complete instantly or within one working day for most partners.
Airlines at 1:1 — Air India Maharaja Club (5 working days), Air France-KLM Flying Blue, British Airways Executive Club, Etihad Guest, EVA Air Infinity MileageLands, JAL Mileage Bank (10 working days), Singapore Airlines KrisFlyer, Qantas Frequent Flyer, Qatar Airways Privilege Club, Thai Airways Royal Orchid Plus, Vietnam Airlines Lotusmiles.
Airlines at worse ratios — Turkish Airlines Miles&Smiles, United MileagePlus and Hainan Airlines Fortune Wings Club all require 2 Reward points per mile. AirAsia rewards runs the other way at 1 point to 3 airasia points, though airasia points are worth very little.
Hotels — ALL Accor Live Limitless, IHG One Rewards, Marriott Bonvoy and Wyndham Rewards all at 1:1; Shangri-La Circle at 5 points to 1.
Accor is the standout. 2,000 Accor points are worth €40, which is why enthusiasts rate Accor transfers well above the ₹1 baseline. HSBC notes the partner list may change; Turkish, United and Hainan were all devalued from 1:1 to 2:1 during 2025, so check the current ratio before you transfer.
Other Benefits
Airport lounges. 6 domestic and 4 international visits every year, with no spend condition attached. Domestic access is delivered through Mastercard and international access through LoungeKey. There is no guest access. HSBC's value calculator describes the visits as available to the primary along with add-on cardmembers, which reads as a shared pool rather than a fresh allocation per card.
Golf. 4 complimentary rounds and 12 complimentary lessons per calendar year, capped at one of each per calendar month, plus 50% off green fees on additional rounds — delivered through the Mastercard World Card India Golf Program.
Travel discounts. 15% off at Yatra (code HSBCTRAVEL1), EaseMyTrip (EMTHSBCT1), Paytm Flights (HSBCTRAVEL) and Cleartrip (CTHSBCTRAVELONE); up to 15% at Goibibo (GOHSBCTRAVEL1); 11% at StayVista (HSBCTRAVEL); and 20% off duty-free at Adani Airports via AdaniOne (HSBCTRAVELONE). Caps run ₹3,000 on domestic bookings and ₹5,000 on international, with StayVista and AdaniOne at ₹3,000. Frequency is generally twice per card per year, and Cleartrip is once every six months.
Dining and entertainment. 10% off up to ₹1,000 with EazyDiner on a minimum bill of ₹3,000, once per card per calendar month, paid through PayEazy. 10% off up to ₹1,000 on dining and on events through the Zomato or District app. Buy one get one free on movie tickets on the District app, worth up to ₹200 on the second ticket, twice per card per calendar month.
Note one discrepancy here. HSBC's product page advertises the EazyDiner benefit as 30% off up to ₹1,000, but the EazyDiner terms and conditions document reserve the 30% construct for HSBC Premier cards (BIN 512042) and give TravelOne cards (BIN 517782) 10% off up to ₹1,000. HSBC's own value calculator also says 10%. Plan around 10%.
Purchase protection. Cover against accidental damage or theft of eligible purchases within India, for 180 days from purchase, with an annual aggregate limit of ₹16,66,600 and a per-occurrence limit of ₹2,49,990. HSBC markets this as up to USD 20,000 a year. It is underwritten by Tata AIG and facilitated through Mastercard, with HSBC acting only as a facilitator. Portable electronics carry 25% depreciation for losses in the first 90 days and 50% from 91 to 180 days, and the exclusion list is long — jewellery, art, cash, consumables, refurbished items, mysterious disappearance and mechanical failure among them. Claims need a phone notification within 24 hours and a signed form within 15 days.
Other. Exclusive privileges at The Bicester Collection villages, including eVIP pass discounts, hands-free shopping and reserved parking, subject to prior registration. Several 2026 reviews also report four complimentary chauffeur airport transfers being added to the card, but this does not appear in the terms and conditions documents or on HSBC's current product page, so treat it as unconfirmed.
Category Restrictions: Where You Won't Earn
No Reward points are earned on the following, identified by merchant category code:
- Fuel (5541, 5983, 5172, 5542, 5552)
- Utilities (4900)
- Insurance (6300, 5960)
- Jewellery (5944, 5094)
- Education and government (9399, 8299, 8220, 8211, 8241, 8244, 8249, 9222, 9402, 9211, 9405)
- Tax payments (9311)
- Real estate agents and managers (6513), which covers most rent payments
- Bail and bond payments (9223)
- Financial institutions (6010-6012) and non-financial institutions (6051)
- Money transfers (4829) and e-wallets (6540)
On top of that, Instant EMI transactions earn no Reward points, and points are not reinstated if an EMI is cancelled or pre-closed. Cash advances and fees earn nothing. Rent payments additionally attract a 1% processing fee plus taxes.
This is a longer exclusion list than most competing travel cards carry, and it is the single most important thing to check against your own spending before applying.
Fees and Charges
| Charge | Amount |
|---|---|
| Joining fee | ₹4,999 + GST |
| Annual fee | ₹4,999 + GST, fully reversed above ₹8,00,000 of eligible annual spend |
| Add-on card fee | Nil |
| Interest-free period | Up to 45 days |
| Finance charges | 3.75% per month (45% per annum) from the transaction date |
| Foreign currency markup | 3.5% plus GST |
| Cash advance fee | 2.5% of the amount, minimum ₹500 |
| Cash advance limit | 20% of the credit limit |
| Late payment fee | 100% of Minimum Payment Due, minimum ₹250, maximum ₹1,200 per month |
| Overlimit fee | 2.5% of the overlimit amount or ₹500, whichever is higher, plus GST |
| Payment return / bounced cheque | ₹500 |
| Cash payment at branch | ₹100 |
| Rental and related payments | 1% processing fee plus taxes |
| Fuel surcharge | 1% of transaction value, no waiver on this card |
| Balance transfer | 1.5% processing fee, minimum ₹200; interest 10.99% to 15.99% per annum |
| ATM cash withdrawal against bank account | ₹100 overseas, nil at non-HSBC ATMs in India |
The late payment fee applies only if the minimum payment due does not reach HSBC within three days of the payment due date. GST at 18% applies to all fees, charges and interest.
One point deserves emphasis. The 3.5% forex markup plus GST works out to roughly 4.13%, against a 4% earn rate on foreign currency spends. The net return on international spending is therefore marginally negative. For a card marketed on travel, that is the largest single weakness in the product.
Is the HSBC TravelOne Credit Card Worth It?
For the right profile, yes — and there are not many alternatives left. If you spend ₹8,00,000 or more a year so the fee reverses, book flights and hotels through the Travel with Points portal, and redeem into Accor, KrisFlyer, Flying Blue or Qatar Avios, this is currently the strongest flexible-miles proposition available to new applicants in India. The 20-partner network with instant in-app transfers and no annual redemption cap on base points is genuinely difficult to match at ₹4,999.
It is a poor fit if your spending is weighted towards the exclusion list. Someone paying school fees, insurance premiums, rent, utilities and tax on a credit card will watch most of their spend earn nothing while still technically counting towards the fee waiver — which flatters the waiver maths and hides how little the card is actually returning. It is also a poor choice as your primary international spending card despite the marketing, because the forex markup cancels the accelerated earn rate. Pair it with a low-markup or zero-markup card for actual overseas payments and use the TravelOne for the booking itself.
If you do not care about miles and would rather have straightforward cashback or voucher value, look elsewhere. Reward points valued at ₹0.20 in the voucher catalogue tell a very different story from ₹1 in KrisFlyer.
Frequently Asked Questions (FAQs)
What is the annual fee for the HSBC TravelOne Credit Card and how do I get it waived? The joining fee and the annual fee are both ₹4,999 plus GST. The annual fee including GST is fully reversed if total eligible spend across the primary and add-on cards exceeds ₹8,00,000 during the relevant anniversary year.
How many Reward points do I earn per ₹100? You earn 4 Reward points per ₹100 on flights, travel aggregators and foreign currency transactions, and 2 Reward points per ₹100 on all other eligible spends. The base rate is uncapped; the accelerated rate is capped at a reported 50,000 accelerated points per calendar month.
What is a Reward point worth? HSBC's own value calculator uses ₹1 per point for redemptions on Apple products or Travel with Points, and most airline partners transfer at 1:1, so a point is roughly equivalent to a mile. Voucher and merchandise redemptions in the Rewards Marketplace are worth considerably less.
Which airlines and hotels can I transfer points to? Fifteen airlines and five hotel programmes, twenty in total. Air India, Singapore Airlines KrisFlyer, British Airways, Qatar Airways, Etihad, Flying Blue, JAL, Qantas, Thai Airways, EVA Air and Vietnam Airlines transfer at 1:1. Turkish, United and Hainan need 2 points per mile. Accor, IHG, Marriott and Wyndham transfer at 1:1, and Shangri-La at 5:1.
What is HSBC Travel with Points? It is HSBC's own booking portal inside the India mobile app, run with Hopper, offering flights, hotels and car rentals. Hotel bookings earn 24 points per ₹100 and flights and car rentals earn 16 points per ₹100, subject to a shared cap of 18,000 accelerated points per calendar month. Fares on the portal can be higher than elsewhere, so compare before booking.
Does the HSBC TravelOne have a fuel surcharge waiver? No. A 1% fuel surcharge applies and the ₹400 to ₹4,000 waiver available on some other HSBC variants is marked as not applicable for TravelOne in the Key Fact Statement. Fuel spends also earn no Reward points.
What is the forex markup? 3.5% plus GST, which is about 4.13% all-in. Since foreign currency spends earn 4%, the net return on international transactions is slightly negative.
How many lounge visits do I get? Six domestic and four international airport lounge visits every year, with no minimum spend condition. Domestic access runs through Mastercard and international access through LoungeKey. There is no complimentary guest access.
Do my Reward points expire? Secondary sources report that points are valid for 36 months from when they are earned. This is not stated in the terms and conditions documents reviewed here, and HSBC Singapore's version of the programme uses a 37-month rule, so confirm the current position with HSBC before letting a balance sit.
Which spends earn no points at all? Fuel, utilities, insurance, jewellery, education, government and tax payments, rent and real estate, e-wallet loads, money transfers, financial and non-financial institutions, bail and bond payments, cash advances, fees, and Instant EMI transactions.
Do excluded categories still count towards the fee waiver and milestone? Yes for the fee waiver and the milestone, in the sense that they are eligible retail spend even though they earn no points. Cash advances, finance charges, late payment charges, balance transfers and annual fees count towards neither.
Is the card available to self-employed applicants? Yes. Self-employed applicants must be aged 25 to 65 with a minimum annual income of ₹12,00,000, against 18 to 65 and ₹6,00,000 for salaried applicants.
Sources: HSBC India Most Important Terms and Conditions, Credit Card Key Fact Statement, TravelOne introductory offer T&C, milestone offer T&C, purchase protection policy T&C, merchant offer T&Cs for Yatra, EaseMyTrip, Paytm, Cleartrip, Goibibo, StayVista, AdaniOne, EazyDiner and Zomato, the TravelOne value calculator, and the HSBC India TravelOne product and rewards pages. Monthly accelerated caps, Travel with Points earn rates, lounge providers, the MCC exclusion list and reward point expiry are drawn from independent card publications and are not stated in the bank's own uploaded documents. All figures verified as at 3 August 2026. Fees, rates, caps, partner ratios and merchant offers are subject to change at the bank's discretion; most merchant offers listed here expire on 31 December 2026. Please confirm current terms with HSBC before applying.
Cards Mentioned in This Article